

Is a Career in Financial Planning Worth It? Honest Review
Table of Contents
- The Verdict: Is a Career in Financial Planning Worth It?
- Financial Planner Career Pros and Cons
- A Day in the Life of a Financial Planner
- Financial Planner Qualifications UK: What You Need to Get In
- Financial Planning Career Progression: Where the Role Can Take You
- Who Thrives in a Financial Planning Career, and Who Does Not
- Conclusion: Weighing It Up for Yourself
- Frequently Asked Questions
Last Updated: October 7, 2026
The Verdict: Is a Career in Financial Planning Worth It?
For most people who enjoy solving problems and building long-term relationships, the question of whether a career in financial planning is worth it is answered with a clear yes. The work combines technical knowledge with genuine human impact, and qualified advisers remain in steady demand across the UK. This guide from SMG Nexus examines the rewards, the trade-offs, and the qualification route so readers can judge the fit for themselves.
SMG Nexus Building Your Financial Advisory Career - A Practical Guide To Buliding A Successful Financial Advice Business
Financial planning is the professional practice of helping clients organise their finances to meet life goals, from retirement and investments to protection and tax efficiency. It rewards patience and people skills as much as technical ability.
The honest answer depends on what a person wants from work. Those who value autonomy, continuous learning and client trust tend to thrive. Those seeking quick wins or predictable routines often find the reality harder than expected.
Below, the rewards and demands are set out plainly, along with the qualifications and progression routes that shape the early years.
Financial Planner Career Pros and Cons
The financial planner career pros and cons come down to a simple trade: meaningful work and independence, balanced against study demands and client-facing pressure. Neither side is hidden from new entrants, but both deserve clear-eyed consideration.
The Rewards: What Makes the Work Worthwhile
Helping a client retire comfortably or protect their family is genuinely satisfying work. Advisers often describe the moment a long-term plan comes together as the reason they stay in the profession.
- Autonomy over how the working week is structured
- Intellectual variety across tax, pensions, investments and protection
- Trusted relationships that deepen over years, not transactions
- Clear progression from paraplanner to adviser to senior or specialist roles
The Trade-Offs: What the Job Demands
Study and exams often run alongside the day job, particularly during the early stages of an adviser’s career. The CII Diploma units require consistent revision, and candidates who underestimate that commitment often find the first year overwhelming.
Client expectations add pressure. People bring their retirement, their savings and their worries to these meetings, and they expect clear answers. Advisers who cannot explain complex ideas simply will struggle, regardless of technical knowledge.
Income can also take time to build. New advisers often earn less in the first year or two while they complete qualifications and grow a client base.
Consideration |
Reward |
Trade-Off |
|---|---|---|
Qualifications |
Deep, respected expertise |
Study and exams alongside work |
Client work |
Trusted long-term relationships |
Emotional weight of client decisions |
Income |
Strong long-term earning potential |
Slower start while building a book |
Flexibility |
Control over schedule and specialism |
Self-generated client pipeline for some roles |
A Day in the Life of a Financial Planner
A typical day blends client meetings, preparation and admin. Most planners spend the morning reviewing files and the afternoon in client conversations, with research and follow-up filling the gaps.
A day in the life of a financial planner rarely looks identical twice. One morning might involve a retirement review with a couple nearing sixty; the next could be a protection discussion with a young family.
- Reviewing client files and preparing recommendations
- Meeting clients to discuss goals, concerns and changes
- Researching products and building suitability reports
- Following up with providers and updating records
Financial Planner Qualifications UK: What You Need to Get In
The main route into the profession runs through the CII Diploma in Regulated Financial Planning. It covers six core units, and most employers expect candidates to complete them while working.
Financial planner qualifications UK entrants usually start with R01, which covers financial services, regulation and ethics. From there, R02 to R06 build the technical and practical knowledge required for client-facing advice.
- R01: Financial Services, Regulation and Ethics
- R02: Investment Principles and Risk
- R03: Personal Taxation
- R04: Pensions and Retirement Planning
- R05: Financial Protection
- R06: Financial Planning Practice
The Chartered Insurance Institute's qualification framework sets out the full syllabus and assessment standards for each unit. Candidates should check current requirements directly, as these can change.
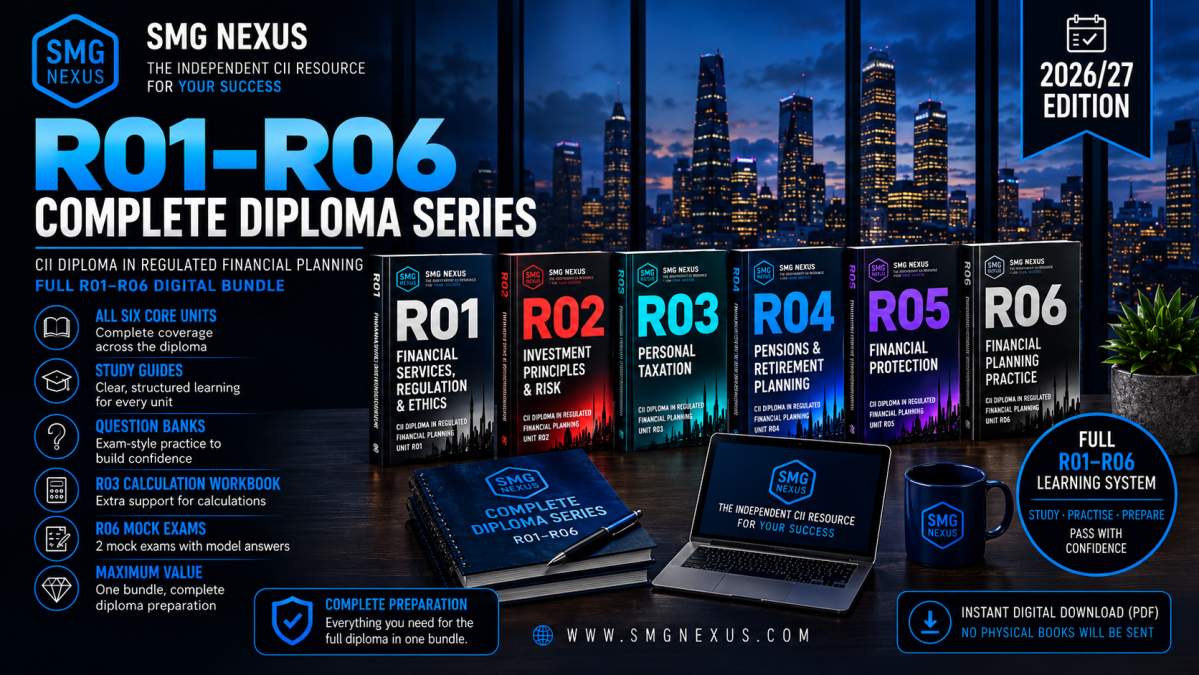
SMG Nexus Complete Diploma Series - 2026/27 Digital Edition
Study materials matter as much as commitment. SMG Nexus provides an independent alternative to traditional training providers, with CII R01-R06 study guides, question banks and calculation workbook (R03) designed to build understanding rather than rote memorisation.
Financial Planning Career Progression: Where the Role Can Take You
Financial planning career progression usually follows a clear path. Many entrants start as paraplanners, move into adviser roles once qualified, and later specialise or move into management.
SMG Nexus Building Your Financial Advisory Career — A Practical Start-up Guide →
Paraplanner roles offer a practical entry point. They build technical knowledge and client familiarity without the immediate pressure of generating business.
From there, progression typically looks like this:
- Trainee or paraplanner: supporting advisers, building technical foundations
- Qualified adviser: managing a client base and giving regulated advice
- Senior adviser or specialist: focusing on complex cases or a niche market
- Management or business ownership: leading teams or running a practice
Some advisers move into compliance, training or technical consultancy. These routes suit people who enjoy the detail more than the client-facing side.
For those considering the business-building route, the Financial Conduct Authority's approach to adviser regulation is worth reviewing early, since it shapes how firms must operate. SMG Nexus also publishes a practical start-up guide for aspiring advisers covering market positioning, client acquisition and compliance systems.
Who Thrives in a Financial Planning Career, and Who Does Not
People who thrive in financial planning tend to be patient, curious and genuinely interested in others. They enjoy explaining complex ideas and are comfortable with the long game, both in client relationships and in their own career.
Those who struggle often want faster results or dislike the study load. The qualification journey is not optional, and it runs alongside full-time work for most candidates.
Honest self-assessment matters here. Someone who dislikes exams, finds client conversations draining, or wants a predictable nine-to-five may find the profession frustrating rather than rewarding.
The reverse is also true. For someone who enjoys learning, values trust over transactions and wants work that visibly improves clients' lives, few careers offer a better combination.
Conclusion: Weighing It Up for Yourself
The question of whether a career in financial planning is worth it has no single answer, because it depends on temperament as much as opportunity. The profession rewards those who commit to the qualification path, build genuine client relationships and keep learning throughout their careers.
For readers ready to take the next step, structured study materials make that path more manageable. SMG Nexus offers CII R01-R06 study guides, question banks and the Complete Diploma Series, all designed to build knowledge and exam confidence. Get started with SMG Nexus and prepare for your CII exams with resources built for the way you actually study.
Frequently Asked Questions
Is financial planning a good career?
It can be, if you value client relationships, structured problem-solving and steady professional development. The work suits people who enjoy explaining complex ideas clearly and building long-term trust. The trade-offs are real too: exam study takes years, and early roles often involve admin or paraplanning before you advise clients directly. Weigh the rewards against the effort honestly before committing.
What does a financial planner do day to day?
A typical day mixes client meetings with preparation and follow-up. You might review a client's circumstances, draft a suitability report, research products, update files and handle compliance checks. Paraplanners and administrators support much of this behind the scenes. No two days look identical, but the rhythm usually involves a blend of face-to-face or video meetings and desk-based analysis.
What qualifications do you need to become a financial planner?
Most people start with the CII Diploma in Regulated Financial Planning, which covers units R01 to R06. R01 covers regulation and ethics, R02 investments, R03 taxation, R04 pensions, R05 protection and R06 planning practice. Some employers also expect progress toward Chartered status later. Study guides, question banks and calculation workbooks can help you work through each unit steadily.
Can you earn a good living as a financial planner?
Earnings vary widely depending on your route, location and whether you work employed or self-employed. Advisers who build a solid client base and progress to senior or Chartered roles often see income grow over time. Early-career pay is usually modest while you complete qualifications. The SMG Nexus Building Your Financial Advisory Career guide covers practical steps for building a client base.